Companies Balk At IRS’ 401(k) Student Loan Matching Guidelines

by Daniel Johnson
October 30, 2024
Employers have been reluctant to implement the IRS’s guidance because they are concerned about additional complexities.
The IRS issued guidance on how companies can use 401(k) matching to match an employee’s contribution to their student loan payments, but some employers have been slow to implement this ruling.
According to Bloomberg Law, employers have been reluctant to implement the IRS’ guidance because they are concerned about additional complexities presented by the ruling, even though Fidelity Investments, SoFi Technologies, and Betterment LLC have already offered to create services to provide student loan matching.
Employees are also wary about implementing the new IRS guidelines as they watch how the federal government approaches student loan forgiveness.
However, according to the IRS guidelines, employers are permitted to count the repayments as part of the employee’s deferred retirement, which allows employees who take part in the 401(k) matching program to save for their eventual retirement while they pay off student loan debt.
“The problem is not the student loans; the problem is the cost of education,” Betsy Mayotte, president and founder of the Institute of Student Loan Affairs, told Bloomberg Law. “We can put as many [bandages] and antibiotics on the student loan issue to make things easier for borrowers, and we should continue to do that, but we are treating the wound and not trying to prevent it from happening in the first place.”
As of Sept. 30, Verizon Communications Inc., Chipotle, and Abbott Laboratories are among the companies that have decided to utilize the 401(k) student loan matching program, but there are concerns.
“This guidance is certainly welcome and helpful, but they (employers) want to make sure there’s additional relief available to the extent that there are foot faults; those can be easily corrected,” Gabe Marinaro, a partner at Akerman LLP, told Bloomberg Law.
Barry Salkin, part of Wagner Law Group’s counsel, told the outlet that risk-averse employers don’t really want to add too many elements to their existing 401(k) plans. “Setting up a plan, things can go wrong,” he added, “but I don’t classify it as a high-risk proposition like offering cryptocurrency.”
As it stands currently, the major roadblocks to the widespread adoption of these plans are data collection and verification issues.
“Actually proving that people are making student loan payments, that they’re not falling behind on them or taking options like forbearance and deferment, is something that still needs to be clarified,” financial consultant Raya Reaves, the owner of City Girl Savings, told Bloomberg Law.
In part, data collection has become more difficult because of 2020’s STOP Act, intended to protect data against scams targeting student loan debtors, according to Jantz Hoffman, the chairman of the Certified Student Loan Board of Standards.
“STOP Act data limitations are creating a situation where it’s very difficult for any of these plan administrators to administer a plan that has the matching component to it because the automated way of receiving that data is nonexistent,” Hoffman told Bloomberg Law. “They’re also not going to want to take on the heavy burden of cost, making their employees enroll in a portal and send payments through that to verify because that’s expensive.”
Hoffman also said some employers want to make sure they’re not favoring a small portion of their workforce.
RELATED CONTENT: 401(k) Matching: The ‘Free Money’ Benefit Every Employee Should Know About
Europeans Opting For Higher Paying US-Based Roles
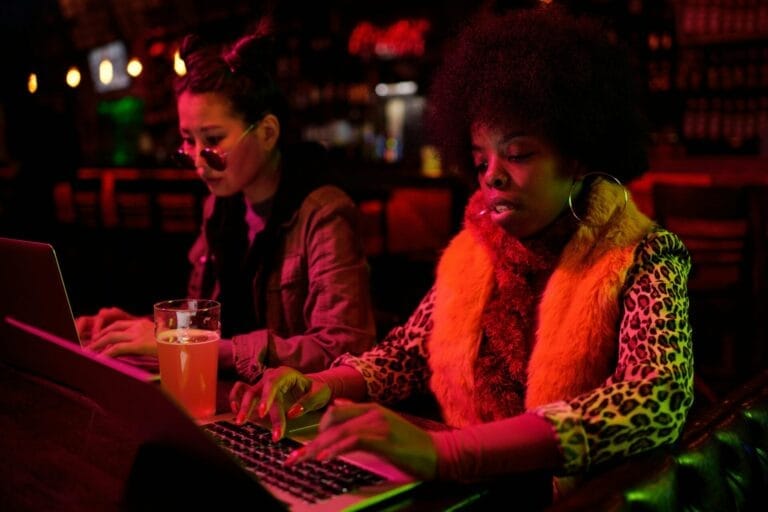
UK-based remote workers are opting for late-night US-based roles to receive higher pay.
With Americans earning, on average, 20% to 40% more than their European counterparts, an increasing number of UK residents are choosing to work night shifts to take on U.S.-based roles.
A new report highlights the rise in European remote workers taking on full- to part-time jobs in America to gain greater work flexibility and higher pay. Market research indicates that software engineers in the U.S. typically earn around $115,000, while the average in Europe varies by region and is about $75,000. A similar disparity exists for marketing managers, with U.S. salaries averaging $107,000 compared to Europe’s average of $70,000.
While it isn’t rare for Europeans to work American jobs, the shift to remote work following the pandemic has opened the floodgates, allowing Europeans to secure positions traditionally reserved for American workers.
“I’ve been working remotely for over a decade, but during the pandemic, many companies finally seemed to acknowledge time zone differences and adjusted accordingly,” Irish marketing executive Laura Mundow tells Fortune.
European workers have found what works for them when it comes to scheduling their day. Some break up the day to complete their initial tasks during the European morning when coworkers are less likely to interrupt with calls, emails, or instant messages and reserve the afternoon for video conference calls.
“I don’t need to be at my desk for eight hours straight,” says Romanian video and audio editor Otinel Mezin. “I can stay nearby and return to my computer if any urgent editing requests come in.”
Cultural differences also play a significant role in UK staffers’ working with US companies. American companies tend to operate at a faster pace, with a more assertive approach to sales and more open conversations about salaries than European companies. However, despite these contrasts, many Europeans say they have come to appreciate innovation and optimism.
“I really love working with Americans,” Mundow says. “There’s an openness there that you might not get in Europe. The stereotype of work being a massive focus for Americans is true. That might not suit everybody. It suits me, but I can see how it could be jarring if work weren’t a central part of your life.”
“I find clients to be more polite in the way they request work and not haggling over prices,” Mezin adds.
European workers encourage other UK-based remote workers to know their worth and avoid undervaluing their work due to location. Once a competitive salary is secured, Mudow recommends living in a country where your earnings stretch further than the U.S. or UK would.
“If you’re earning American money, you can live very well somewhere that is not America,” she says.
JPMorgan Chase Sues Customers For Exploiting Viral ‘Infinite Money Glitch’

by Keka Araújo
October 30, 2024
These civil cases mark the beginning of the bank’s broader legal campaign against those it accuses of fraudulently obtaining funds through the ATM loophole.
JPMorgan Chase, the largest U.S. bank by assets, has filed lawsuits against customers who allegedly exploited a technical glitch to withdraw substantial funds from ATMs before their deposited checks bounced.
The lawsuits, filed in at least three federal courts on Oct. 28, target individuals who allegedly withdrew the most significant amounts in the so-called “infinite money glitch,” a scheme that gained viral popularity on social media platforms such as TikTok in late August.
The most significant case filed involves a Houston man who, according to JPMorgan, owes $290,939.47 after an unidentified accomplice deposited a counterfeit check totaling $335,000 at an ATM.
“On Aug. 29, 2024, a masked man deposited a check in [the] defendant’s Chase bank account in the amount of $335,000,” JPMorgan stated in the Texas filing. “After the check was deposited, the defendant began withdrawing most of the ill-gotten funds.”
In the wake of the viral glitch, JPMorgan reportedly investigated thousands of cases involving varying sums. While the bank has not disclosed the total financial impact, its investigation has highlighted an ongoing challenge with check fraud—a global issue resulting in losses of $26.6 billion last year alone, according to Nasdaq’s Global Financial Crime Report. Although the use of paper checks has declined, JPMorgan’s “infinite money glitch” episode underscores how social media can amplify vulnerabilities within financial institutions.
The glitch was reportedly corrected a few days after discovery, allowing customers to bypass the usual waiting period banks impose for checks to clear. Under normal conditions, only a portion of a check’s value is available for immediate withdrawal, with the remainder accessible only after the check clears, which can take several days.
Beyond the Texas case, JPMorgan has filed additional lawsuits in Miami and California involving customers accused of withdrawing amounts ranging from $80,000 to $141,000. According to individuals familiar with the bank’s internal investigation, most cases involve smaller sums, though JPMorgan prioritized cases with higher amounts and those with potential connections to organized criminal groups.
According to court documents, JPMorgan’s security team contacted those suspected of committing fraud, seeking repayment for the phony checks under the terms of the bank’s deposit agreement. The bank’s lawsuits demand restitution of the funds, interest, overdraft fees, and, in some instances, punitive damages. The financial institution is also seeking compensation for legal costs associated with the recovery efforts.
These civil cases mark the beginning of the bank’s broader legal campaign against those it accuses of fraudulently obtaining funds through the ATM loophole. Alongside its civil suits, JPMorgan has reportedly referred cases to law enforcement agencies nationwide, paving the way for potential criminal charges. According to sources familiar with the bank’s approach, this strategy signals that JPMorgan will actively pursue offenders, focusing on cases indicating possible links to organized fraud groups.
“Fraud is a crime that impacts everyone and undermines trust in the banking system,” said Drew Pusateri, a JPMorgan spokesperson, in a statement to CNBC. “We’re pursuing these cases and actively cooperating with law enforcement to make sure if someone is committing fraud against Chase and its customers, they’re held accountable.”
The lawsuits represent JPMorgan’s commitment to recovering funds lost through ATM fraud and serve as a warning to discourage similar schemes. The bank’s proactive stance also reflects a growing awareness of how social media can facilitate the rapid exploitation of financial vulnerabilities, underscoring the evolving landscape of bank security.
RELATED CONTENT: 100 Hungry Raccoons Pull Up To White Woman’s Crib, She’s Been Feeding Them For Years
How AI Is Pushing The New Trend Of ‘Silent Firing’

Are you worried about AI stealing your job?
The rise of artificial intelligence (AI) has reportedly prompted a new trend in the workforce called “silent firing,” Fast Company reports.
Silent firing is the inverse of quiet quitting, a trend that gained popularity during the COVID-19 pandemic, where employees would do the bare minimum as a fast track to being fired with severance. The silent firing move is where employers are making jobs harder in hopes that people will quit so their positions will be automated.
Experts like George Kailas, CEO of Prospero.Ai, feel that certain employers are making the office experience unbearable on purpose, especially tech companies. “So when Amazon is pushing a five-day in-office workweek, despite the fact that 90% of their employees are “dissatisfied” and 73% are considering quitting, it doesn’t really fit with the “cool tech office” vibes of the past,” Kailas wrote.
“Maybe Amazon is silently firing workers by making the workplace inhospitable. Because the best way to decrease retention while saving on severance would be to remove remote work.”
Studies from Live Data Technologies show that employee growth of big tech companies has fluctuated over the past two years. In 2022, the count increased by 5% and then went down. The trend happened again in March 2024 as the hiring numbers went up again, only to decrease just two months later in May.
Artificial intelligence is blamed for the alarming numbers, but other experts aren’t buying it. According to the New York Post, MIT professor and economist Daron Acemoglu claims that only 5% of jobs can be replaced or work with AI over the next 10 years and states the technology is simply not reliable enough. “A lot of money is going to get wasted. “You’re not going to get an economic revolution out of that 5%,” Acemoglu said.
“You need highly reliable information or the ability of these models to faithfully implement certain steps that previously workers were doing. They can do that in a few places with some human supervisory oversight … but in most places they cannot.”
Kailas insists that nearly 18% of people who once worked for big tech companies between 2023 and 2024 are still unemployed since “AI is booming and the rest of the labor market is stagnant and/or declining if you look at the unemployment numbers.”
Lack of engagement may also contribute to those claims. Gallup survey results showed a 5% decrease in engagement among Gen Z and young millennials. Richard Wahlquist, CEO of the American Staffing Association, says that close to three in 10 employees overall aren’t actively engaged at work.