Shannon Sharpe Recalls Bad Financial Advice About Google
by Jeroslyn JoVonn
October 11, 2024
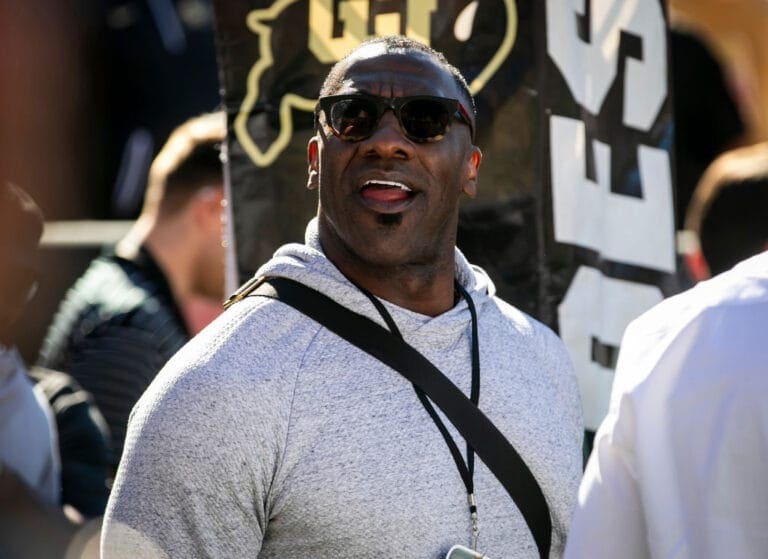
Shannon Sharpe wishes he invested in Google 20 years ago when he had the chance.
Shannon Sharpe believes he’d be a part of the Billionaire Boys Club today if he hadn’t taken poor financial advice years ago.
During a conversation about money and investing with business mogul and Dallas Mavericks owner Mark Cuban on his Club Shay Shay platform, Sharpe recounted how he once considered an early investment in Google, but decided against it after his financial advisor advised him not to.
“I remember when Google came out, and they thought the shares were going to open up at about $85 a share,” Sharpe recalled. “And I remember saying to my financial guys, ‘You know what, I’ve just signed with the Ravens, I have some money. Man, I’d like to buy $300,000 worth [of Google shares].’”
Sharpe’s financial advisor thought Google’s shares were overpriced at $115 and convinced him to pass on the investment. Reflecting on it now, Sharpe realizes how much he could have gained in the long run had he purchased the stock at that price. Sharpe also noted an early investment opportunity in Netflix that he passed up.
“That motherf— ther!” Sharpe exclaimed to Cuban. “I’d have been a billionaire with you!”
“You f—ked up,” Cuban said with a laugh.
After a 14-season NFL career and transitioning into becoming a successful sports commentator and podcast host, Sharpe has built a net worth of $14 million. During his time in the NFL, he earned $22.3 million in salary, which included a four-year $13.8 million contract with the Baltimore Ravens in 2000 and a $16 million deal with the Denver Broncos in 2002.
Since retiring, Sharpe has served as a sports commentator on CBS Sports, Fox Sports, and ESPN. His latest commentary can be found on ESPN First Take with Stephen A. Smith. Sharpe also crafted a cognac he can be seen drinking on his Club Shay Shay platform, Le Portier Shay VSOP Cognac.
Considered one of the best tight ends in NFL history, Sharpe ranks third in career receptions, receiving yards, and touchdowns for his position. In 2011, he was inducted into the Pro Football Hall of Fame.
Taxpayers To Recieve More Standard Deductions On 2025 Income Taxes

by Daniel Johnson
October 23, 2024
Republicans have pledged to reinstate Trump’s tax bill after it expires in 2025, but the Tax Policy Center analyzed that 83% of the tax cuts would go to the top 1% in 2027.
The Internal Revenue Service’s annual inflation adjustments, released on Oct. 22, show that American taxpayers will receive higher standard deductions on their 2025 income taxes.
According to ABC News, single taxpayers and married taxpayers filing separately will see a $400 boost, bringing their total in standard deductions to $15,000 for 2025.
Couples who file jointly will see an $800 bump, taking their standard deduction up to $30,000, and heads of households will receive a $600 increase from the amount on 2024’s income taxes, bringing their total to $22,500.
Overall, while income thresholds for income tax brackets scaled up, the top tax rate remains at 37% for individuals who earn more than $626,050 for single taxpayers.
That figure is nearly $20,000 more than in 2024 when $609,350 put a single taxpayer in the highest bracket.
The IRS makes these inflation adjustments yearly, and inflation has featured prominently in the national conversation.
Even though the overall inflation rate is at its lowest rate in nearly three years, some price points reveal that certain industries, such as medical care, the airline industry, auto insurance, and clothes, are still more expensive than they were pre-pandemic.
Although the standard deductions are higher in dollar amount than last year, the increases are lower than in recent years.
For example, between the 2023 and 2024 tax year, single-filer deductions increased by $750, while married couples and heads of households saw their deductions increase by $1,500 and 1,100, respectively.
According to The Washington Post, the IRS announcement marks the last year of the Trump-era Tax Cuts and Jobs Act. Unless Congress extends the law, the rates will revert to previous levels, including a top tax rate of 39.6%.
The expensive tax cuts are a key piece of the economic proposals from former President Donald Trump’s campaign, and he has vowed to reinstate them should he be elected.
According to Dean Baker, a senior economist at the Center for Economic Policy Research, Trump’s tariff proposal will likely adversely affect middle-class and low-income Americans.
“We should just call them taxes on imports because that’s what they are,” Baker told Vox. “We import $4 trillion of goods every year. So that’s a $400 billion tax increase. That’s really quite a hit that’s overwhelmingly going to moderate-income, middle-class people.”
Vice President Kamala Harris, on the other hand, has indicated that she would allow some of the cuts to expire but has promised not to raise taxes on households with an income below $400,000.
According to Vox, Trump’s tax bill was a mixed bag, offering a few positives like an expanded child tax credit and an increased standard deduction; their analysis also showed that the bill had a friendlier tax rate for people making higher incomes than it did for people who make less.
Republicans have pledged to reinstate the bill after it expires in 2025, but the Tax Policy Center analyzed that 83% of the tax cuts would go to the top 1% in 2027.
Lily Batchelder, a New York University professor who worked under President Obama, told the outlet that the bill was essentially crafted to benefit the rich.
“The bill is investing heavily in the wealthy and their children — by boosting the value of their stock portfolios, creating new loopholes for them to avoid tax on their labor income, and cutting taxes on massive inheritances,” Batchelder said.
Batchelder continued, “At the same time, it leaves low- and middle-income workers with even fewer resources to invest in their children and increases the number of Americans without health insurance.”
RELATED CONTENT: Here’s How Vice President Kamala Harris’ Economic Plan Would Help Black Americans
Flau’Jae Johnson Purchases 20 Acres Of Land In Atlanta

by Daniel Johnson
October 15, 2024
LSU women’s basketball star and rapper says the purchase represents something bigger than her burgeoning careers.
LSU women’s basketball star and rapper Flau’Jae Johnson recently purchased a 20-acre tract of land in Atlanta.
As Johnson told Boardroom, “This land represents more than just an investment for me—it’s about building something bigger than basketball or music. I want to create opportunities for my community and leave a legacy that shows young women, especially young Black women, that we can do it all.”
According to World Population Review, the average price of an acre of land in Georgia is $30,000, which puts the price of Johnson’s purchase at roughly $600,000.
According to Sportskeeda, Johnson’s NIL value is roughly $1.4 million, (although it notes that figure currently leads women’s college basketball, Juju Watkins’ groundbreaking Nike and Gatorade deals will likely shift those valuations)
In 2023, Essence reported that Kia Brooks, Johnson’s mother, had brokered approximately $2 million in NIL deals for Johnson with names like Puma, JBL, and Papa John.
At the time, Johnson told the outlet that it was important for her to carve out space for the Black girls and women who would be following her into the NIL space.
“It feels great to be one of the NCAA players that’s leading the NIL movement,” Johnson said. “You know, as a Black woman, just as a woman in general, it’s so hard for us to dominate in these spaces and to be one of the top athletes it’s just something I worked for my entire life. I never thought it would come from basketball. I always thought it would be music. But to see that it’s happening in both is amazing.”
Johnson continued, “I think it’s important for little girls to see girls that look like them on big national campaigns like this—and it’s just important for women’s basketball. It’s important for the marketing of everything that we’re trying to do for women’s sports in general. So making history in that way, it feels amazing. And I just appreciate the opportunities that have been given to me.”
As Johnson has seen her star rise through a new EP featuring Lil Wayne and a performance at the ESPYS,, it is clear she is most likely going to be getting more of those opportunities.
However, as Johnson told SiriusXM College, those opportunities are contingent upon her success on the court.
“This is what I always tell people. They think like, ‘Oh my gosh, you’re getting all these NIL deals. You’re getting all this money.’ But if I wasn’t doing somewhat good on the court, that wouldn’t be a thing,” Johnson said. “At the end of the day, they still want to sponsor me because I’m a good athlete and we win.”
RELATED CONTENT: LSU Star Flau’Jae Johnson Gives 10K To Native Boys & Girls Club
Overpayments And Future Benefit Cuts Loom

by Keka Araújo
October 16, 2024
While improper payments represent less than 1% of the total benefits paid out during that period, the $23 billion in uncollected overpayments is a major concern for the SSA.
Social Security, already under significant financial pressure, has a staggering $23 billion in unrecovered overpayments.
Between Fiscal Years (FY) 2015 and 2022, the Social Security Administration (SSA) issued nearly $72 billion in improper payments, most of which were overpayments. This comes as the program faces a looming financial crisis, with its trust funds projected to be depleted by 2035, potentially leading to a 25% reduction in benefits for millions of Americans.
While improper payments represent less than 1% of the total benefits paid out during that period, the $23 billion in uncollected overpayments is a major concern for the SSA, according to its Office of the Inspector General (OIG). These overpayments—often the result of errors or beneficiary misreporting—highlight the agency’s struggle to maintain financial accuracy in its payments.
Since 2002, the OIG has flagged improper payments as a “major management challenge” and made dozens of recommendations for preventing and correcting them. However, despite repeated audits and advice, many of these recommendations remain unimplemented, which has exacerbated the SSA’s ability to recover funds and prevent future overpayments.
According to OIG audits, one of the primary reasons for improper payments is the SSA’s reliance on beneficiaries to self-report changes in their circumstances, such as income or living arrangements, which affect payment amounts. A lack of sufficient controls in the SSA’s automated and manual processes further complicates the issue. The OIG has urged the SSA to obtain more accurate data from external sources, such as other federal agencies and financial institutions, to better assess eligibility and payment amounts.
Despite these ongoing challenges, the SSA has made some progress. In October 2023, the agency began a comprehensive review of its overpayment procedures and is developing new systems to access third-party payroll data. This could reduce improper payments, particularly for beneficiaries who work while receiving benefits.
However, efforts to implement a new debt management product—intended to address several OIG recommendations—were halted in FY 2024 due to a lack of funding. This has left many critical issues unresolved, impeding the ability to recover overpayments effectively.
“Improper payments have been a longstanding challenge for SSA,” said Michelle L. Anderson, Assistant Inspector General for Audit and Acting Inspector General. “While the Agency has taken actions to address this challenge, it needs to do more.”
With Social Security’s financial future hanging in the balance, addressing improper payments is crucial for the program’s solvency. Preventing and recovering overpayments won’t fully resolve the crisis, but it is a critical step in ensuring that Social Security can continue to provide for millions of Americans who rely on it for their livelihood.
RELATED CONTENT: Mississippi Governor Sings Praises Of Ole Miss Counterprotesters After ‘Star-Spangled Banner’ Shenanigans
Can Credit Card Debt Become Uncollectible? It Depends On Location

by Mitti Hicks
October 11, 2024
The average American carries an overall balance of about $6501 on their credit cards, according to Experian, and as more people search for debt relief, there are some questions about whether credit card debt can come uncollectible?
August marked a historic moment for Americans. A report from the Federal Reserve Bank of New York found that Americans owed a record $1.14 trillion on their credit cards. Credit card balances reportedly rose by $27 billion in the second quarter of 2024, which is a nearly 6% increase from a year ago.
Unfortunately, credit card delinquency rates are also higher. In the second quarter of 2024, 7% of households reported serious delinquency (90 days or more) on their credit cards, compared to 5% at the same time in 2023.
Vonda Copeland, co-owner of Copeland Insurance Agency, told CBS News that with the current economy, high interest rates, and job insecurity, more people are relying on credit cards for basic needs. It’s a disastrous recipe, unfortunately, for falling behind on payments.
The average American carries an overall balance of about $6,501 on their credit cards, according to Experian, and as more people search for debt relief, there are some questions about whether credit card debt can come uncollectible. Turns out, it depends on a number of factors, including the credit card user’s location.
Factors That Lead To Uncollectible Debt
James Lambridis, founder and CEO of DebtMD said creditors usually sell unpaid debt to collection agencies from anywhere between three and six months. Most agencies try to retire anywhere between 20 and 40% of the original balance.
Credit card debt becomes uncollectible after three main factors: expiration of the statute of limitations, bankruptcy filings, and creditors decision to write off the debt.
When the statute of limitations are involved, it begins when creditors begin sending calls and letters to collect payment towards the debt.
“If the debt remains unpaid for the duration specified by the statute of limitations — usually between three to ten years depending on the state — the creditor loses the legal right to sue for repayment,” Kristy Kim, CEO and co-founder of TomoCredit said, adding that the debt legally becomes time-barred and legally uncollectible.
Even though creditors lose their right to sue or garnish wages against borrowers when debt becomes uncollectible, Kim says debt can still appear on your credit report and impact your score for up to seven years.
RELATED CONTENT: How To Stop The Credit Bureaus From Giving Your Information To Potential Lenders